
Categories
Home Buying Tips, Home Selling Tips, Mortgage Rates, Kansas City Real Estate, Kansas City Area TrendsPublished October 22, 2026
3-2-1 Seller-Paid Buydown: Why the Right Agent Matters for Buyers and Sellers Right Now
About the author: Ken Hoover has lived in Platte County for more than 20 years and helps buyers and sellers across the Kansas City metro through Ken Hoover Real Estate Group.
What a 3-2-1 Buydown Really Is
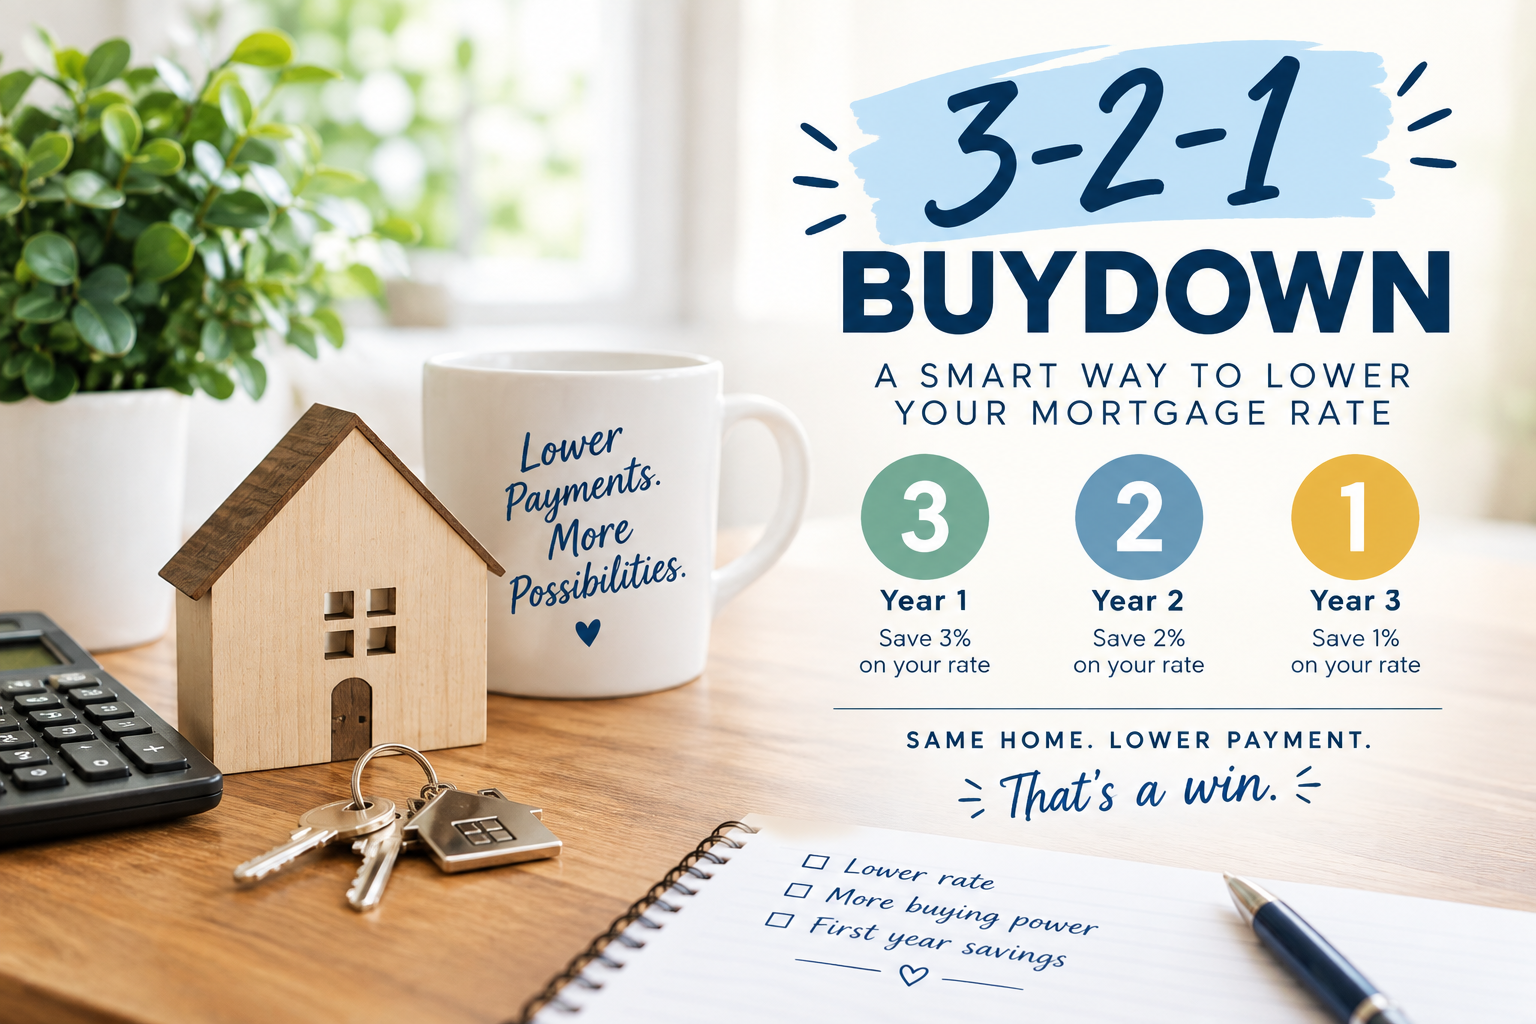
A 3-2-1 buydown is real money that follows the buyer and helps lower the payment. When the seller pays for it, the buyer's payment is figured at 3 percentage points below the note rate in year one, 2 points below in year two, and 1 point below in year three. In year four, the payment settles at the full note rate. The loan amount and the note rate on the loan do not change.
The seller's money is deposited at closing and held in an escrow account. Each month, part of it is applied to the buyer's payment so the lender still receives the full amount.
A Real Example With Real Numbers
Freddie Mac reported the average 30-year fixed rate at 7.03% on September 24, 2026. Here is an illustration on a $330,000 loan at 7.03%. The full principal and interest payment would be about $2,202 a month.
- Year 1, payment figured at 4.03%: about $1,581 a month, or about $621 less
- Year 2, payment figured at 5.03%: about $1,778 a month, or about $425 less
- Year 3, payment figured at 6.03%: about $1,985 a month, or about $217 less
- Year 4 and beyond: about $2,202 a month at the full note rate
That adds up to roughly $15,150 in payment relief over the first three years. These numbers cover principal and interest only. Taxes, insurance, mortgage insurance, and HOA dues are not reduced, and your lender will give you exact figures for your loan.
Why Buyers Come Out Ahead Right Now
Here is how I look at it. I believe buyers have the most leverage right now, and a 3-2-1 buydown lets a buyer use that leverage to get the payment they want today. Instead of waiting and competing with a crowd of other buyers when rates fall, you can buy now with a lower payment while the seller helps carry the cost.
The buyer still has to qualify at the full note rate, and the payment steps up each year, so you should be comfortable with the full payment before you count on the savings. Refinancing later is never guaranteed, so I never tell a buyer to plan around it.
Why Sellers Come Out Ahead Too
Sellers get more money, and buyers get the payment they want. When we explain how a buydown can net the seller more than a straight price cut, it is also more attractive to buyers. A price reduction lowers what the home sells for. A buydown lets the seller hold the price and put the concession where the buyer feels it most, in the monthly payment.
Every loan program has its own limits on how much a seller can contribute. On VA loans, for example, a seller-paid buydown counts toward the 4 percent limit on seller concessions. I walk every seller through the numbers before we agree to anything, so you can see what you net with a buydown compared to a price reduction.
Why the Agent and Lender You Choose Matter
Not all agents know how this works or the advantages it can bring. My advice is to only work with an experienced agent and a lender who knows how to do it. Not all lenders have this program, so ask early. The buydown also has to be written into the contract the right way and set up correctly at closing, and that is where experience matters.
If you are looking for a lender who offers this, I recommend Stephen Smith at Envoy Mortgage, (314) 239-8558, stephen.smith@envoymortgage.com.
Your 3-2-1 Buydown Game Plan
- Talk to a lender who offers the 3-2-1 program before you start shopping, and ask them to run your payment for each year.
- Buyers: ask for a seller-paid buydown in your offer, and compare it with a price reduction.
- Sellers: ask your agent to show your net with a buydown compared to a price cut.
- Make sure you are comfortable with the full payment in year four.
- Work with an experienced agent who has structured these deals before.
Ready to Talk About a 3-2-1 Buydown?
If you are buying or selling in the Kansas City area and want to see what a 3-2-1 buydown could look like for you, call or text me at (816) 210-2027 or start a home search at KenHooverSells.com.

Ken Hoover | Ken Hoover Real Estate Group
Keller Williams Kansas City North | Powered by Place
Serving the Greater Kansas City Metro Area | Kansas and Missouri
Call or text (816) 210-2027
KenHooverSells@gmail.com
6222 N Chatham Ave, Kansas City, MO 64151
KenHooverSells.com
Keller Williams Kansas City North | 816-452-4200
Each Office Independently Owned & Operated
Equal Housing Opportunity

Ken Hoover
Operator | Ken Hoover Real Estate Group | Keller Williams Realty Kansas City North
or another way