
Categories
Home Buying Tips, Homeownership Advice, Kansas City Real Estate, Mortgage Rates, Platte County, Closing CostsPublished October 14, 2026
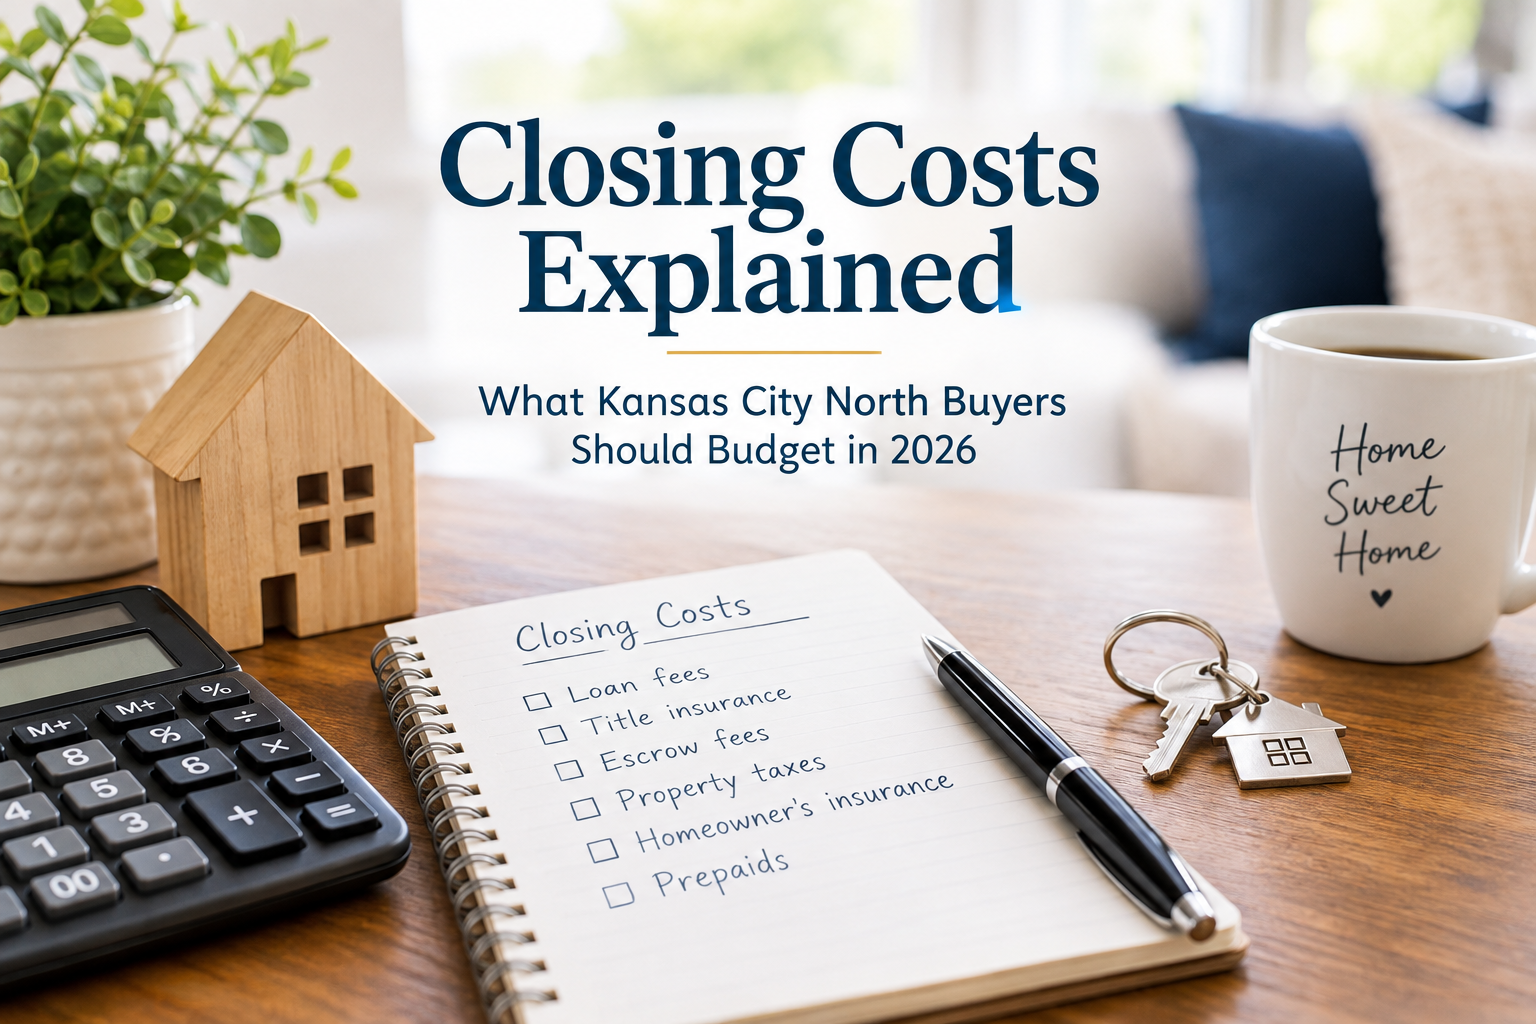
Closing Costs Explained: What Kansas City North Buyers Should Budget in 2026
About the author: Ken Hoover has lived in Platte County for more than 20 years and helps buyers and sellers across Kansas City North, the Northland, and the greater Kansas City metro.
Closing Costs Surprise More Buyers Than the Down Payment
Most buyers I talk with have a down payment number in their head. Far fewer have a number for closing costs, and that is the one that tends to catch people off guard in the last week before closing. I would rather you hear about it from me today than from a closing statement later.
This matters more right now because borrowing is not cheap. Freddie Mac's weekly survey released October 8, 2026 put the average 30-year fixed rate at 7.40%. When the rate is higher, every dollar you keep in your pocket at closing matters, so it pays to understand where the money goes and what you can negotiate.
What Closing Costs Usually Run in Missouri
Closing costs are the fees you pay to finalize the loan and transfer the home, on top of your down payment. According to Rocket Mortgage's March 2026 Missouri guide, buyers here typically pay roughly 3.8% of the purchase price, which works out to about $10,700 on a home at the state median sale price of $275,700 (Redfin data cited in that guide). Your number will move up or down with your loan type, your lender, your county, and the price of the home.
Where the Money Actually Goes
Here are the main buckets I walk buyers through:
- Lender fees: application, origination, underwriting, credit report, and sometimes a rate lock.
- Third-party reports: the appraisal your lender orders, plus your home inspection and any extras like a radon test or sewer scope.
- Title and settlement: the title search, lender's title insurance, and closing or escrow fees.
- Prepaids and escrow: your first year of homeowners insurance, some prepaid property taxes, and interest from closing day to the end of the month.
- Mortgage insurance: if you put down less than 20% on a conventional loan, or an FHA loan's upfront and monthly premiums.
Some of these, like the inspection and appraisal, you often pay along the way before closing day. Property taxes and insurance are partly prepaid, which is why the total can feel larger than the fees alone.
An Illustration: A $325,000 Northland Home
An illustration, not a quote or a specific client: imagine a buyer purchasing a $325,000 home. At 3% to 4% of the price, closing costs would run about $9,750 to $13,000, and that is in addition to the down payment. If the buyer is also paying a few hundred dollars each for a radon test and a sewer scope, that cash needs to be set aside early. Your actual numbers depend on your loan and your lender, so use this only as a starting point for your own budget.
Ways to Lower Your Cash to Close
You have more options than most buyers realize. Here are the ones I bring up first:
- Ask the seller for help. A seller concession is a credit toward your closing costs that we negotiate in the contract. The amount allowed depends on your loan type and down payment, and it is easier to get when the home has been sitting or the seller is motivated.
- Compare lender credits to discount points. A lender credit can cut your cash at closing in exchange for a slightly higher rate, while points do the opposite. Which is better depends on how long you plan to stay in the home.
- Watch your closing date. Because you prepay interest from closing day to month's end, closing late in the month usually means a smaller prepaid interest bill.
- Look into down payment assistance. Programs through the Missouri Housing Development Commission may help with down payment or closing costs for eligible buyers, and each has its own income and credit rules.
Know Your Numbers Early: Your Loan Estimate
Lenders are required to give you a Loan Estimate within three business days of your application, and a Closing Disclosure at least three business days before closing. Compare the two line by line. If anything jumped, ask why. A good lender will welcome that conversation.
Getting pre-approved before you shop gives you real numbers instead of guesses. I recommend Stephen Smith at Envoy Mortgage (314-239-8558, stephen.smith@envoymortgage.com). He can walk you through your estimated closing costs, your payment, and your loan options. You can also find more on our financing page.
Your Kansas City North Closing Cost Game Plan
- Get pre-approved early and ask for a written estimate of your cash to close.
- Budget 3% to 4% of the purchase price for closing costs, in addition to your down payment.
- Set aside cash for your inspection, radon test, and sewer scope.
- Talk with me before you write an offer about asking for a seller credit.
- Compare your Loan Estimate and Closing Disclosure line by line.
- Ask about down payment assistance if you qualify.
Ready to see what buying would really cost? Start with my buyer resources, browse current Kansas City listings, or call or text me at (816) 210-2027 and we will map out your numbers together. If you are also thinking of selling first, you can get a free home value estimate here.
Sources: Freddie Mac Primary Mortgage Market Survey, week of October 8, 2026; Rocket Mortgage, Average Closing Costs in Missouri (March 2026), citing Redfin median sale price data. Figures are estimates and will vary by lender, loan type, and property.
Ken Hoover | Ken Hoover Real Estate Group
Keller Williams Kansas City North | Powered by Place
Serving the Greater Kansas City Metro Area | Kansas and Missouri
Call or text (816) 210-2027
KenHooverSells@gmail.com
6222 N Chatham Ave, Kansas City, MO 64151
KenHooverSells.com

Keller Williams Kansas City North | 816-452-4200
Each Office Independently Owned & Operated
Equal Housing Opportunity
Ken Hoover
Operator | Ken Hoover Real Estate Group | Keller Williams Realty Kansas City North
or another way